LA Mortgage Rates: Price Cut vs Rate Buydown (Nov 2026)
By Armond Ohan, NMLS #540169
Media in this article is hidden until you allow optional external media in Privacy Choices.
Los Angeles Mortgage Rates: Price Cut or Rate Buydown?
By Armond Ohan • November 2, 2026 • 4 minute read
Thinking about buying or selling a home in Los Angeles? Mortgage rates held close to steady this week, and fewer new homes hit the market. Here is what that means for you, in plain English.
Los Angeles Mortgage Rates Held Steady This Week
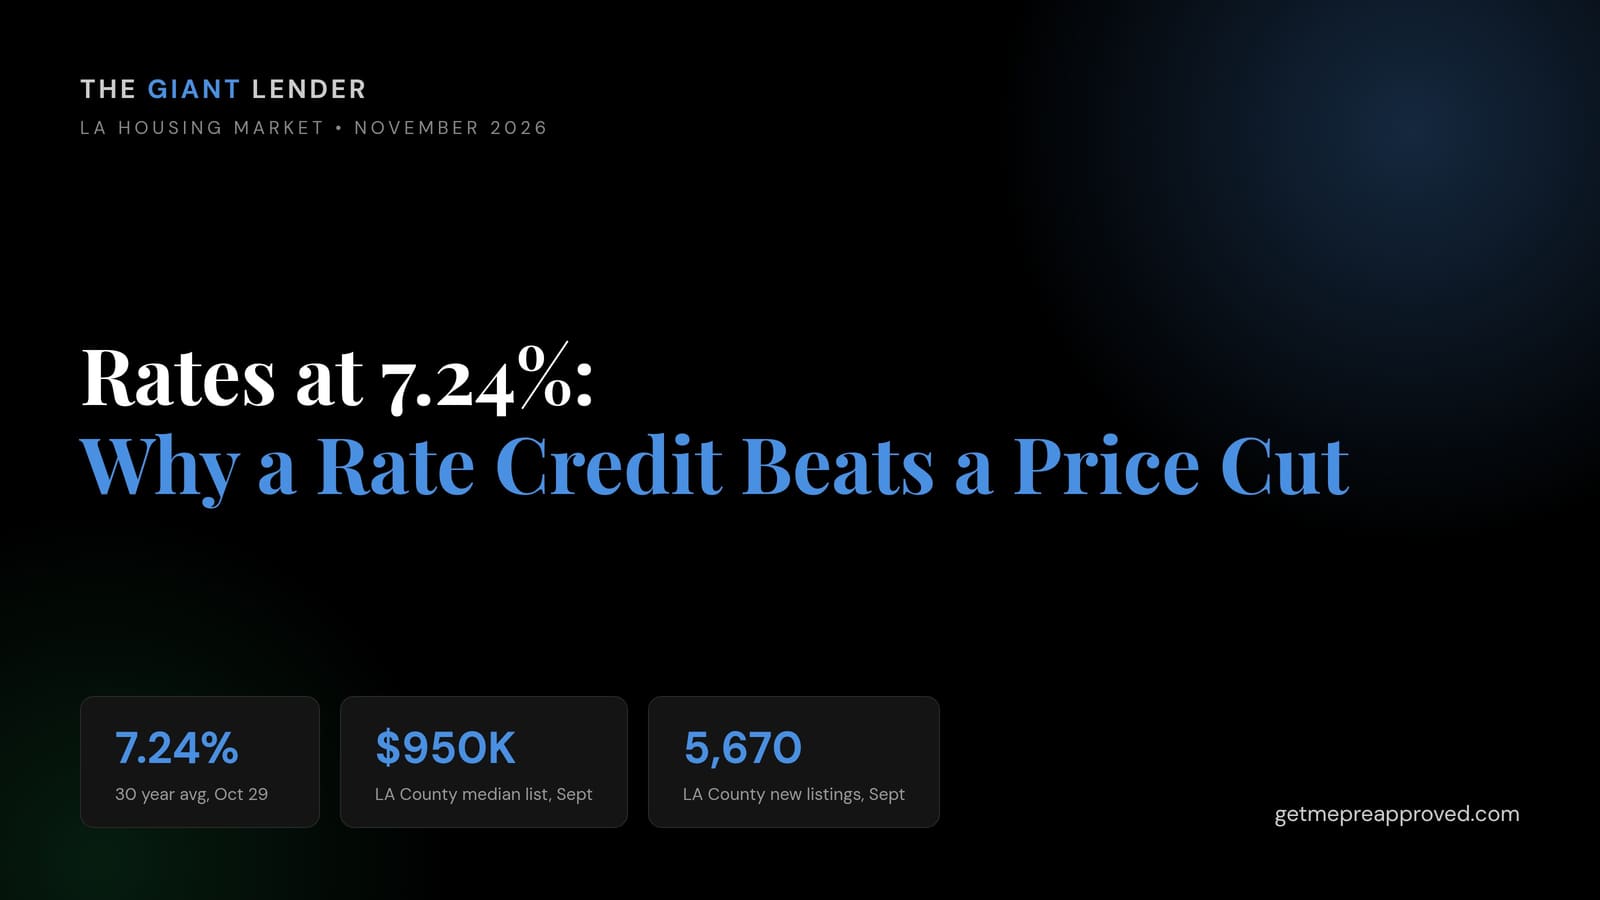
The average 30 year fixed rate was 7.24% on Thursday, October 29, according to Freddie Mac. That is down from 7.32% the week before. A year ago it was 6.17%.
What does that mean for you? On a $760,000 loan over 30 years, 7.24% works out to about $5,179 a month in principal and interest. Every small drop in rate takes real money off that bill. The next weekly number comes out this Thursday.
What Is Happening in LA County
Fewer new homes came on the market in September. LA County had 5,670 new listings, the lowest of any month so far this year. The median list price was $950,000, which is $45,000 lower than September of last year.
Homes are also taking a little longer to sell. The typical listing sat 56 days in September, up from 54 days in August. So buyers have some time, and sellers have a reason to stand out.
What This Means If You Are Buying
Ask for help with your rate, not just a lower price. Here is a simple example. On a $950,000 home with 20% down, a $7,600 price drop lowers your payment about $41 a month. If the seller puts that same $7,600 toward buying down your rate by about a quarter point, your payment drops about $128 a month. Same money from the seller. About three times the savings for you. Want to run your own numbers? Try our mortgage calculator or see how much home you can afford.
Selling in LA: Seller Buydown vs Price Cut
Before you cut your price, think about offering to pay down the buyer's rate. It costs you the same, but it gives buyers a lower monthly payment, and the payment is what they shop for. It also keeps your price where it is, which helps protect what nearby homes are worth. With fewer new listings coming in, a home with a payment offer stands out.
Did A Bank Say No To You?
If you are self employed, a bank may have told you that your tax returns do not show enough income. That does not have to be the end. You may be able to qualify using your bank deposits instead of your tax returns. If you buy rentals, you may be able to qualify based on the rent the home brings in, not your personal income. See qualifying with bank deposits and financing for rental homes. Bank said no? I say yes.
Common Questions
What is a seller paid rate buydown?
The seller puts money toward lowering the buyer's interest rate instead of lowering the price. In our example, $7,600 lowers the rate by about a quarter point and cuts the monthly payment about $128.
Is a rate buydown better than a price cut in Los Angeles?
Often, yes, for the monthly payment. With the same $7,600, a price cut saved about $41 a month while a buydown saved about $128 a month. Your numbers depend on the price, the down payment, and the rate you qualify for.
What are mortgage rates in Los Angeles right now?
The national average 30 year fixed rate was 7.24% on October 29, 2026, per Freddie Mac. Your own rate depends on your credit, down payment, and the home. Get a free quote at getmepreapproved.com.
The Bottom Line
Rates did not move much, but the LA market is giving both sides room to deal. Buyers, ask about your payment. Sellers, a rate offer can beat a price cut. Read more on our Los Angeles home buying blog.
Want to know exactly what you qualify for? Getting preapproved takes minutes and it costs you nothing. Start at getmepreapproved.com or call me directly at 626.823.8278.
Armond Ohan
The Giant Lender, Powered by 7 Mortgage
NMLS #540169
611 N Brand Blvd Ste 1300, Glendale, CA 91203
626.823.8278 • Armond@ohangrp.com • @thegiantlender
Sources: Freddie Mac PMMS, Oct 29, 2026; Realtor.com via FRED, LA County data for September 2026 (median list price, new listings, days on market). Payment math: $950,000 price, 20% down, $760,000 loan, 30 year fixed, principal and interest only, 7.24% versus 6.99% assumed after a 1 point buydown.
National averages shown. Your rate depends on your situation. This is not an offer of credit. All loans subject to qualification.